Categories
Real Estate

Insurance Lenders Are Taking More CRE Risk

Insurance companies are taking on a larger and more aggressive role in commercial real estate lending, accepting higher loan-to-value ratios and greater credit risk than they have historically. This shift is partly driven by private-equity ownership of insurance platforms, which is pushing these lenders toward broader participation in private credit markets. The sector already carries substantial CRE exposure and faces a wave of upcoming loan maturities, a combination that could intensify pressure on borrowers if interest rates remain elevated. As traditional banks continue pulling back, insurance lenders are increasingly filling that void and becoming a meaningful force in CRE private credit.

Our Take

For private market investors, the growing role of insurance lenders in commercial real estate is a development worth watching closely. These are not small players. Insurance companies manage enormous pools of long-duration capital, and when they shift their lending appetite, it reshapes the financing landscape for the entire asset class. The fact that they are now accepting higher loan-to-value ratios and greater credit risk signals a meaningful change in how this capital is being deployed.

From an underwriting perspective, this shift deserves careful interpretation. On one hand, more active lenders in the market creates more options for borrowers, which can be a positive. On the other hand, when any large capital source begins loosening its standards, it tends to push risk into parts of the market that may not be well equipped to absorb it. The article notes that private-equity ownership is encouraging insurance lenders to participate more broadly in private credit, which suggests return pressure, not just opportunity, is driving this behavior.

For investors in private credit, the practical implication is that the competitive environment is evolving. Insurance lenders filling gaps left by traditional banks adds liquidity to the market, but it also compresses the opportunity set for disciplined lenders who have maintained conservative standards throughout this cycle. The key is not simply having access to deals, it is having the underwriting discipline to distinguish between loans that are attractively priced for their risk and those that are not.

The mention of significant upcoming loan maturities in the insurance sector’s CRE portfolio is also worth noting. If rates stay elevated and those loans need to be refinanced or restructured, it could create stress in specific pockets of the market. In short, the landscape is becoming more complex, and that complexity rewards patient capital paired with rigorous credit analysis over yield-chasing at the expense of structure.

Source: Insurance Lenders Embrace Risk In CRE Loans — Bisnow

If you’re curious about how our approach could fit into your portfolio, schedule a call to connect with our team. We’d love to talk through what we’re seeing and where we’re going next.

Categories
Real Estate

Rising Bond Yields Do Not Always Signal Market Stress

A recent sell-off in U.S. Treasury bonds has pushed bond yields higher, prompting concern among some investors. According to Business Insider, analysts suggest the rise in yields is not a signal of crisis but rather a reflection of growing confidence in the U.S. economy’s ability to handle elevated interest rates. Investors appear to be adjusting their expectations around economic growth and Federal Reserve policy, not reacting to runaway inflation or fiscal instability. The stock market’s relative resilience during this period is cited as further evidence that the move in yields is orderly rather than alarming.

Our Take

For investors watching interest rates, the instinct to treat rising bond yields as a warning sign is understandable. But the distinction between yields rising because of fear and yields rising because of confidence matters enormously. According to Business Insider, the current move reflects the latter: markets are recalibrating their expectations around growth and Fed policy, not signaling a breakdown in economic fundamentals.

For private market investors, this framing changes the conversation considerably. A yield environment driven by economic resilience is very different from one driven by inflation panic or credit stress. When yields climb because investors believe the economy can sustain higher rates, it typically means the underlying conditions that support real estate demand, stable employment, business activity, and consumer spending remain intact. That is a meaningful distinction when evaluating whether to deploy capital or sit on the sidelines.

From an underwriting perspective, the practical challenge remains the same: higher rates mean higher borrowing costs, and those costs have to be absorbed somewhere in the deal structure. What disciplined underwriting accounts for is not just the rate environment today, but the trajectory and the reasoning behind it. When the data suggests yields are moving on growth expectations rather than on distress signals, the case for patient capital and durable assets becomes clearer, not murkier.

The key takeaway is that not all rate moves are created equal. The stock market’s relative stability during this period, as noted in the article, reinforces that markets are reading this as a growth story rather than a risk-off event. For investors in private real estate and credit, that context supports a posture of selective, disciplined deployment rather than retreat. In short, the environment rewards those who can read the signal clearly and act accordingly.

Source: Why investors should stop panicking about the latest rise in bond yields — Business Insider

If you’re curious about how our approach could fit into your portfolio, schedule a call to connect with our team. We’d love to talk through what we’re seeing and where we’re going next.

Categories
Real Estate

Why Long-Term Rates May Stay Higher Than Investors Expect

A recent memo from Oaktree Capital takes direct aim at the U.S. Treasury’s effort to suppress rising long-term interest rates through expanded bond buybacks. The memo argues this intervention treats symptoms rather than causes, with the underlying pressures being persistent inflation, fiscal deficits running near 6% of GDP, and surging capital demand driven by AI investment. The author’s conclusion is straightforward: artificially holding yields down is a temporary measure that could ultimately backfire, and the only real solution is fiscal discipline through a combination of spending restraint and revenue increases that stabilize the national debt relative to the size of the economy.

Our Take

When one of the most respected voices in global investing publishes a memo arguing that the U.S. Treasury is treating a fever with an ice pack, investors should pay attention. The core message from Oaktree Capital is not that markets are broken, but that government intervention cannot substitute for fiscal fundamentals. For private market investors, that distinction matters more than it might appear.

For investors, the practical concern is not the bond buyback program itself, but what it signals about the broader rate environment. If fiscal deficits near 6% of GDP continue, and if capital demand from AI investment keeps climbing, the structural pressure on long-term rates does not simply vanish because the Treasury steps in to buy bonds. Oaktree’s argument is that these forces are too large and too persistent to be neutralized by a single policy tool. That means investors should plan around rates that remain elevated for longer than many models assumed even a year ago.

From an underwriting perspective, this environment demands discipline. When long-term rates stay high, the cost of capital stays high, which compresses the margin for error on any leveraged investment. Durable cash flow becomes more valuable, not less, because it is the only reliable anchor when financing costs are unrelenting. Conservative leverage matters for the same reason. Deals structured on the assumption that rates would normalize quickly are now showing stress, while deals built on disciplined assumptions continue to perform.

In short, Oaktree’s memo reinforces a view we have held for some time: the path back to a low-rate world runs through genuine fiscal reform, not creative Treasury management. Until that work is done, patient capital and disciplined underwriting are not just virtues. They are the strategy.

Source: Shall We Repeal the Laws of Economics – Part III — Oaktree Capital

If you’re curious about how our approach could fit into your portfolio, schedule a call to connect with our team. We’d love to talk through what we’re seeing and where we’re going next.

Categories
Real Estate

Hiring blew past expectations in August, jobs report shows

U.S. employers added 162,000 jobs in August, far exceeding expectations and marking a sharp turnaround from the prior month’s loss of 23,000 jobs. The August figure also came in well above the average monthly gain over the previous 12 months, signaling that the labor market remains meaningfully stronger than many had anticipated.

Our Take

For private market investors, a jobs report like this one carries more weight than it might first appear. A labor market that keeps adding jobs at above-trend rates is, at its core, a demand story. Employed workers pay rent, fill office space, and support the retail and service businesses that occupy commercial real estate. When hiring surprises to the upside, it reinforces the foundation that income-producing real estate depends on.

From an underwriting perspective, the August rebound is notable precisely because it followed a month of job losses. A single weak month can cloud the picture and tempt investors toward overly cautious conclusions. The recovery in hiring suggests the prior month’s decline was more noise than signal and that the broader trend remains intact. For those evaluating real estate investments with multi-year hold periods, that distinction matters. Durable cash flow projections are only as reliable as the economic conditions supporting them.

For investors focused on long-term demand drivers, employment data also shapes the rate conversation in ways worth tracking. A stronger-than-expected labor market reduces pressure on the Federal Reserve to cut interest rates quickly. That is not necessarily a setback. Rate stability, or even a slower path down, can reflect an economy that continues to perform. Markets that obsess over rate cuts sometimes lose sight of the fact that rate cuts are most urgent when the economy is struggling. This report suggests it is not.

In practical terms, disciplined underwriting in this environment means looking past month-to-month volatility and anchoring to trend-level data. The 12-month average provides that context here, and August’s figure coming in well above it is a constructive signal. Patient capital focused on durable assets in supply-constrained markets is well-positioned when the economic backdrop holds up better than expected. The key takeaway is that the fundamentals supporting real estate demand remain on solid ground.

Source: Hiring blew past expectations in August, jobs report shows — ABC News

If you’re curious about how our approach could fit into your portfolio, schedule a call to connect with our team. We’d love to talk through what we’re seeing and where we’re going next.

Categories
Real Estate

How to Verify a Private Real Estate Manager’s Track Record Before Investing

Key Highlights

A strong track record is not simply a collection of return numbers.

For private real estate investors, the more important question is whether the results can be verified, whether the process behind them is repeatable, and whether the manager demonstrated discipline when conditions did not go according to plan.

Before committing capital, investors should evaluate realized outcomes, underwriting discipline, transparency, capital preservation, and how the manager behaved when the facts changed.

That is the difference between reviewing performance and evaluating a track record.


Start With Realized Results, Not Projected Returns

Imagine an investor considering a $250,000 to $500,000 allocation to a private real estate strategy.

The offering materials show an attractive projected IRR and equity multiple. The properties appear compelling. The manager has a polished presentation and a clear investment thesis.

But none of that answers the first diligence question:

What has the manager actually done?

Projected returns describe what a sponsor believes could happen.

A track record should help investors understand what has already happened.

That means distinguishing between unrealized investments, projected outcomes, and completed transactions. Realized exits can provide useful evidence of whether a manager has successfully moved an investment through acquisition, operation, value creation, and disposition.

Past performance never guarantees future results. But completed transactions provide something projections cannot: evidence of execution.

Verify the Process Behind the Numbers

Even verified performance statistics can be incomplete if investors do not understand how those results were produced.

A 20% return generated through conservative leverage, disciplined operations, and improving property fundamentals tells a different story than the same return generated through aggressive debt or an unusually favorable market movement.

Investors should ask:

  • What was the original business plan?
  • How much leverage supported the investment?
  • What assumptions changed during ownership?
  • How was value actually created?
  • Did results depend heavily on market appreciation?
  • Were projected and realized outcomes materially different?

The objective is not simply to determine whether the manager produced a strong number.

It is to determine whether the underlying investment process appears disciplined and repeatable.

Look at What Happened When Conditions Changed

Track records are often presented through successful transactions.

Investors should also ask about the difficult ones.

Real estate business plans rarely unfold exactly as projected. Interest rates move. Construction costs change. Leasing may take longer. Physical diligence can uncover unexpected capital requirements. Market pricing can shift before an acquisition closes.

Those moments can reveal more about an investment manager than an outperforming exit.

How did the manager respond?

Did the team revise its assumptions when new facts emerged? Did it inject more risk into the deal to preserve the original projection? Did it communicate changes clearly to investors? Was the firm willing to renegotiate or walk away when the economics no longer made sense?

At Hanson Capital, this is an important part of how we think about track record.

Discipline should be visible not only in the transactions a manager completes but also in the decisions that protect capital when circumstances change.

Evaluate Capital Preservation Alongside Return Generation

Private real estate investing involves risk, including the potential loss of principal.

That makes downside management an essential part of manager evaluation.

Sophisticated investors should look beyond the best-performing investments and ask how the manager approaches:

  • Acquisition basis
  • Leverage
  • Capital reserves
  • Property-level risks
  • Tenant concentration
  • Exit assumptions
  • Unexpected capital requirements

A manager focused only on maximizing projected returns may be optimizing a different objective than an investor focused on preserving and compounding capital over time.

At Hanson Capital, underwriting begins with the downside.

The objective is not to make every transaction look attractive. It is to determine whether the investment remains defensible across a range of outcomes.

Reporting Quality Is Part of the Track Record

Track record verification should not stop with transaction performance.

Communication matters.

Investors should understand how frequently a manager reports, what information is provided, and how clearly challenges are disclosed.

Good reporting should help an investor understand:

  • Current property performance
  • Progress against the original business plan
  • Material changes in assumptions
  • Capital expenditures
  • Leasing activity
  • Significant risks or challenges

The most valuable reporting is not necessarily the most optimistic.

It is the reporting that allows investors to understand what is happening with their capital.

Transparency becomes particularly important when performance deviates from the original plan.

Ask Whether the Track Record Is Relevant

A manager may have decades of experience and still lack a relevant track record for the strategy being offered.

If an investor is evaluating a multi-tenant industrial strategy, for example, prior success in an unrelated asset class does not automatically establish expertise in small-bay leasing, industrial property management, tenant improvements, or infill acquisition underwriting.

The same applies geographically.

Local market experience can influence sourcing, tenant relationships, construction knowledge, property operations, and the ability to evaluate replacement cost and acquisition basis.

Investors should therefore ask not only:

“Does this manager have experience?”

But:

“Is that experience relevant to the strategy I am being asked to invest in?”

A Track Record Should Reveal a Decision-Making System

Ultimately, investors are trying to determine whether prior results came from a repeatable investment process.

That process should be visible.

For Hanson Capital, that means focusing on a disciplined acquisition basis, conservative underwriting, operational execution, transparent reporting, and the willingness to change course when the facts no longer support the original thesis.

A credible track record is not proof that every future investment will succeed.

It is evidence that the manager has a framework for deciding where capital should be deployed, how risk should be managed, and when discipline requires a different decision.

That is what investors should be trying to verify.

Before You Invest

A performance table can be useful.

It should not be the end of the diligence process.

Before committing capital to a private real estate manager, investors should verify realized outcomes, understand how returns were generated, evaluate downside discipline, review reporting quality, and determine whether the manager’s experience is relevant to the strategy being offered.

The strongest question is not:

“What returns have you produced?”

It is:

“Can I verify the process that produced them?”

For investors comparing private real estate managers, that distinction can be one of the most important parts of due diligence.

Discuss Your Private Real Estate Allocation

If you’re evaluating a private real estate manager and want to understand how Hanson Capital approaches track record, underwriting discipline, capital alignment, and downside protection, schedule a discussion with our team.

We can walk through our investment process, current small-bay industrial opportunities, and the questions sophisticated investors should be asking before committing capital.


Frequently Asked Questions

What should I look for in a private real estate manager’s track record?

Look beyond headline returns. Evaluate realized exits, investment strategy, leverage, capital preservation, reporting transparency, and how the manager responded when market conditions or individual investments changed.

Why are realized exits important?

Realized exits show what happened after an investment completed its full lifecycle. They can provide more useful evidence of execution than projected returns or unrealized valuations alone.

Does a strong past track record guarantee future real estate returns?

No. Past performance does not guarantee future results. A track record should be viewed as evidence of prior execution and decision-making, not a promise of future performance.

How can I tell whether a manager’s track record is relevant?

Compare the manager’s prior experience with the strategy currently being offered. Consider asset class, geography, business plan, operating requirements, and whether the team has executed similar investments before.

Why does transparency matter when evaluating a real estate sponsor?

Transparency helps investors understand both performance and risk. A manager’s willingness to communicate challenges, changes in assumptions, and business plan adjustments can provide important insight into how the firm manages investor capital.

Categories
Real Estate

CRE Bidding Gains Momentum as Credit Competition Reaches New Highs

Lender competition in commercial real estate credit markets reached a new high in July 2026, with JLL’s Global Bid Intensity Index posting its strongest monthly improvement in a year during June. The increase in competitive pressure among lenders is driving tighter pricing and more favorable terms for borrowers across CRE asset classes. Both private credit providers and banks are showing growing appetite for CRE debt, even as meaningful relief on overall borrowing costs has yet to materialize.

Our Take

For private market investors, the signal here is meaningful: when lenders compete aggressively for the same deals, borrowers gain real leverage. Tighter pricing and improved terms are not just incremental wins. They reflect a structural shift in how capital is flowing back into commercial real estate, and that shift has direct consequences for deal economics and portfolio returns.

From an underwriting perspective, the JLL Global Bid Intensity Index reaching its strongest monthly improvement in a year tells us that the credit markets are not waiting for rate cuts to get moving. Private credit and banks are both stepping forward, which means the competitive dynamic is playing out across multiple lending channels simultaneously. That kind of broad-based participation tends to be more durable than a surge driven by a single capital source.

For investors, this environment creates an interesting duality. On the equity side, more available and competitively priced debt can support better deal structures and improve projected returns on new acquisitions. On the lending side, the same competition that benefits borrowers also compresses yields for lenders, which means disciplined underwriting matters more, not less, when the market heats up. Chasing volume at the expense of credit quality is a risk that surfaces precisely in moments like this.

The key takeaway is that improving credit conditions is a constructive backdrop for patient capital. Markets that had been constrained in recent years are showing genuine signs of thaw. That does not mean every deal makes sense, but it does mean that well-structured transactions with durable cash flow and conservative leverage are increasingly finding the financing they need. In short, the conditions for thoughtful deployment are improving.

Source: CRE Bidding Gains Momentum as Credit Competition Reaches New Highs — GlobeSt

If you’re curious about how our approach could fit into your portfolio, schedule a call to connect with our team. We’d love to talk through what we’re seeing and where we’re going next.

Categories
Real Estate

The Industrial Market Is Splitting: Why Small Bay Is Holding Up While Large-Format Space Resets

Industrial real estate is entering a more selective phase.

After several years of rapid expansion, elevated construction, and exceptional rent growth, the broader market is normalizing. New supply is being absorbed, tenants are making more deliberate leasing decisions, and future rent growth assumptions require greater discipline.

But the adjustment is not occurring evenly.

Large-format distribution facilities are working through a visible supply reset. Small-bay industrial, particularly in established infill locations, continues to reflect a different supply-demand balance.

For investors, the lesson is straightforward:

Industrial is not one market.

The Broader Industrial Market Is Normalizing

CBRE expects overall industrial vacancy to stabilize in the mid-6% range during 2026 as speculative construction declines. Leasing activity may improve modestly, but rent growth is expected to remain subdued as the sector adjusts to slower economic growth, existing first-generation vacancy, and changing trade conditions.

This does not mean the industrial thesis is broken.

It means broad exposure is no longer enough.

The easier phase of the cycle rewarded investors for owning industrial generally. The current phase places greater weight on product type, submarket, tenant demand, acquisition basis, and operating execution.

Those distinctions are becoming increasingly visible between large-format and small-bay properties.

Large-Format Space Carries a Different Risk Profile

Large distribution buildings serve an important role in modern logistics, manufacturing, and supply-chain infrastructure.

Their risk profile, however, differs materially from multi-tenant small-bay industrial.

A large-format property may depend on one national tenant occupying hundreds of thousands of square feet. While that lease can provide stability during occupancy, a departure can eliminate most or all of the asset’s income at once.

Releasing the building may require a long decision cycle tied to a national occupier’s logistics strategy, capital plan, and facility requirements.

New development has also been concentrated heavily in larger industrial facilities. When that supply enters the market as tenant expansion slows, vacancy can increase quickly within the segment.

This is not a criticism of big-box industrial.

It is a recognition that large spaces, concentrated income, and national leasing decisions create a different form of exposure.

Why Small Bay Is Holding Up Differently

Small-bay industrial serves a more localized tenant base.

Contractors, trades, service companies, local suppliers, light manufacturers, last-mile operators, and growing small businesses use these spaces to support daily operations.

Their real estate decisions are often driven by practical questions:

Can crews reach customers efficiently? Is the property close to labor and suppliers? Can materials and equipment move through the space? Does the location support established routes and relationships?

For these tenants, functional industrial space is not discretionary.

Relocation can disrupt staffing, inventory movement, customer access, and operating efficiency. That can support longer occupancy and stronger renewal behavior when the space continues to meet the tenant’s needs.

Small-bay industrial benefits from a durable imbalance: businesses need the space, but relatively little new product is being built where those businesses operate.

Infill Scarcity Strengthens the Thesis

Location matters across industrial real estate, but it is particularly important for small-bay users.

Many of these tenants serve customers within a defined radius. They need proximity to neighborhoods, job sites, commercial corridors, transportation routes, and labor pools.

Established infill locations can provide that access, yet they are difficult to reproduce.

Developable industrial land is limited. Zoning is often restrictive. Construction costs can push required rents beyond what smaller users can reasonably pay. Developers may therefore favor larger facilities that offer greater efficiency at scale.

The result is an aging but strategically important stock of small-bay properties in locations where replacement is economically or physically difficult.

That scarcity can support existing assets, but it does not excuse poor underwriting. Physical condition, functionality, capital requirements, and purchase basis still determine whether a specific property is investable.

Diversification Is Built Into the Rent Roll

Multi-tenant small-bay assets can also reduce income concentration.

Instead of relying on one large occupier, a property may generate rent from multiple businesses operating across different industries. Lease expirations can be staggered, limiting the likelihood that the entire rent roll turns over at once.

This structure creates several potential advantages:

  • Lower dependence on any single tenant
  • Multiple renewal and leasing events
  • Opportunities to address below-market rents incrementally
  • Greater flexibility when one suite becomes vacant
  • More diversified property-level cash flow

For Hanson Capital, diversification is not simply a portfolio objective.

It is built directly into the rent roll.

Preferred Product Does Not Mean Automatic Acquisition

Small-bay industrial remains Hanson Capital’s preferred segment, but that does not make every small-bay opportunity attractive.

Recent acquisition decisions demonstrate the distinction.

Hanson walked away from Point West when diligence uncovered capital exposure that could not be resolved at the required basis. The firm declined San Marcos when stronger tenant interest compressed the yield and removed much of the value-add spread.

Scottsdale advanced after unexpected roof and HVAC exposure was quantified and addressed with the seller. Chandler moved forward because the below-replacement-cost basis, conversion plan, market demand, and all-cash execution remained aligned.

The common thread was not a mandate to buy small bay.

It was a requirement that each investment earn its place through underwriting.

Hanson Capital is not buying the theme. We are underwriting the deal.

Turning Market Selection Into Operational Value

Selecting the right market segment creates an opportunity. It does not complete the investment.

Performance still depends on sourcing, basis discipline, leasing, capital planning, property management, accounting, financing decisions, and day-to-day execution.

That is where Hanson Capital’s integrated platform matters.

Our strategy focuses on infill multi-tenant industrial assets where disciplined management can improve tenant retention, address below-market rents, upgrade the property, and strengthen the durability of the income stream.

The objective is operational alpha, not dependence on broad market appreciation.

Strategic Takeaway

Industrial real estate is not moving in one direction.

Large-format space is working through a more visible supply reset, while small-bay industrial continues to benefit from limited development and local businesses that need functional space near customers, labor, and infrastructure.

That difference matters, but selectivity still matters more.

The opportunity is not in owning industrial broadly. It is in acquiring the right product, in the right infill market, at a defensible basis, and operating it with discipline.

Discuss Current Industrial Opportunities

Schedule a discussion with Hanson Capital to evaluate current multi-tenant small-bay industrial opportunities and potential 1031 exchange replacement property options.


Frequently Asked Questions

Is industrial real estate one market?

No. Industrial real estate includes different product types with different supply, demand, lease structures, tenant profiles, and risk characteristics. Large-format distribution facilities and small-bay industrial properties can perform differently even within the same metro area.

What is small-bay industrial real estate?

Small-bay industrial real estate typically refers to smaller industrial suites used by contractors, trades, local suppliers, light manufacturers, service businesses, and last-mile operators. These tenants often need functional space close to customers, labor, routes, and suppliers.

Why is small-bay industrial different from large-format industrial?

Small-bay industrial often serves local businesses across multiple smaller suites, while large-format industrial may depend on one major tenant occupying a much larger facility. This creates different vacancy risk, income concentration, leasing timelines, and supply exposure.

Why does infill scarcity matter in small-bay industrial?

Infill scarcity matters because many small-bay tenants need locations close to customers, labor, transportation routes, and established business corridors. These locations are difficult to reproduce due to limited land, zoning constraints, and construction costs.

How can multi-tenant industrial assets reduce income concentration?

Multi-tenant industrial assets can spread rental income across multiple tenants and industries. This may reduce dependence on any single occupant and create more granular lease rollover compared with single-tenant or large-format properties.

Does Hanson Capital buy every small-bay industrial opportunity?

No. Hanson Capital favors small-bay industrial, but each acquisition must still meet underwriting standards. Product type alone is not enough. Basis, physical condition, tenant demand, capital needs, and execution risk must all support the investment thesis.

Categories
Real Estate

Fed Hawks Add to CRE Debt Concerns

Hawkish dissents within the Federal Reserve are intensifying concerns across commercial real estate debt markets. According to GlobeSt, the prospect of rates remaining elevated for longer is tightening credit conditions, with rising Treasury yields pushing borrowing costs higher and complicating both loan workouts and new originations across property types. Borrowers facing near-term refinancing pressure are feeling the strain most acutely, as policy uncertainty makes it harder for lenders and borrowers alike to plan around a clear rate path.

Our Take

For private market investors, the more consequential story here is not the Fed’s headline rate but the uncertainty surrounding how long that rate stays where it is. When policymakers are visibly divided, lenders grow cautious and borrowers grow hesitant. That combination slows transaction volume, stretches timelines on loan resolutions, and keeps pricing in a state of flux that makes disciplined underwriting both harder and more valuable.

From an underwriting perspective, elevated Treasury yields matter because they set the floor for what lenders must charge to generate an acceptable return. When that floor rises and stays elevated, the cost of new debt increases across nearly every property type. For borrowers who took on floating-rate loans or shorter maturities during the low-rate era, the refinancing math has become genuinely difficult. The article points to this refinancing pressure as a central concern, and it is not hard to see why. A borrower who locked in favorable terms several years ago and now faces a loan maturity in a high-rate environment has limited options and limited leverage.

For investors with patient capital and conservative leverage, however, this environment is not simply a challenge. It is a source of opportunity. When conventional lenders pull back and credit conditions tighten, well-capitalized private lenders can step into that gap on more favorable terms. The assets do not disappear. The demand for capital does not disappear. What changes is who provides it and at what price.

In short, the current environment rewards exactly the kind of disciplined approach that separates long-term investors from opportunistic ones. The key takeaway is that uncertainty, managed carefully, can be a competitive advantage for those who are prepared to act with clarity while others wait for conditions to settle.

Source: Fed Hawks Add to CRE Debt Concerns — GlobeSt

If you’re curious about how our approach could fit into your portfolio, schedule a call to connect with our team. We’d love to talk through what we’re seeing and where we’re going next.

Categories
Real Estate

Buying Into Oversupply, Converting Into Undersupply: Hanson Capital’s Chandler Small-Bay Strategy

Industrial real estate is not one uniform market.

Large-format vacancy and small-bay scarcity can exist within the same submarket at the same time. Understanding that distinction can create opportunities that broad vacancy statistics fail to capture.

Hanson Capital’s acquisition at 235 S. 56th Street in Chandler, Arizona, is built around that market mismatch.

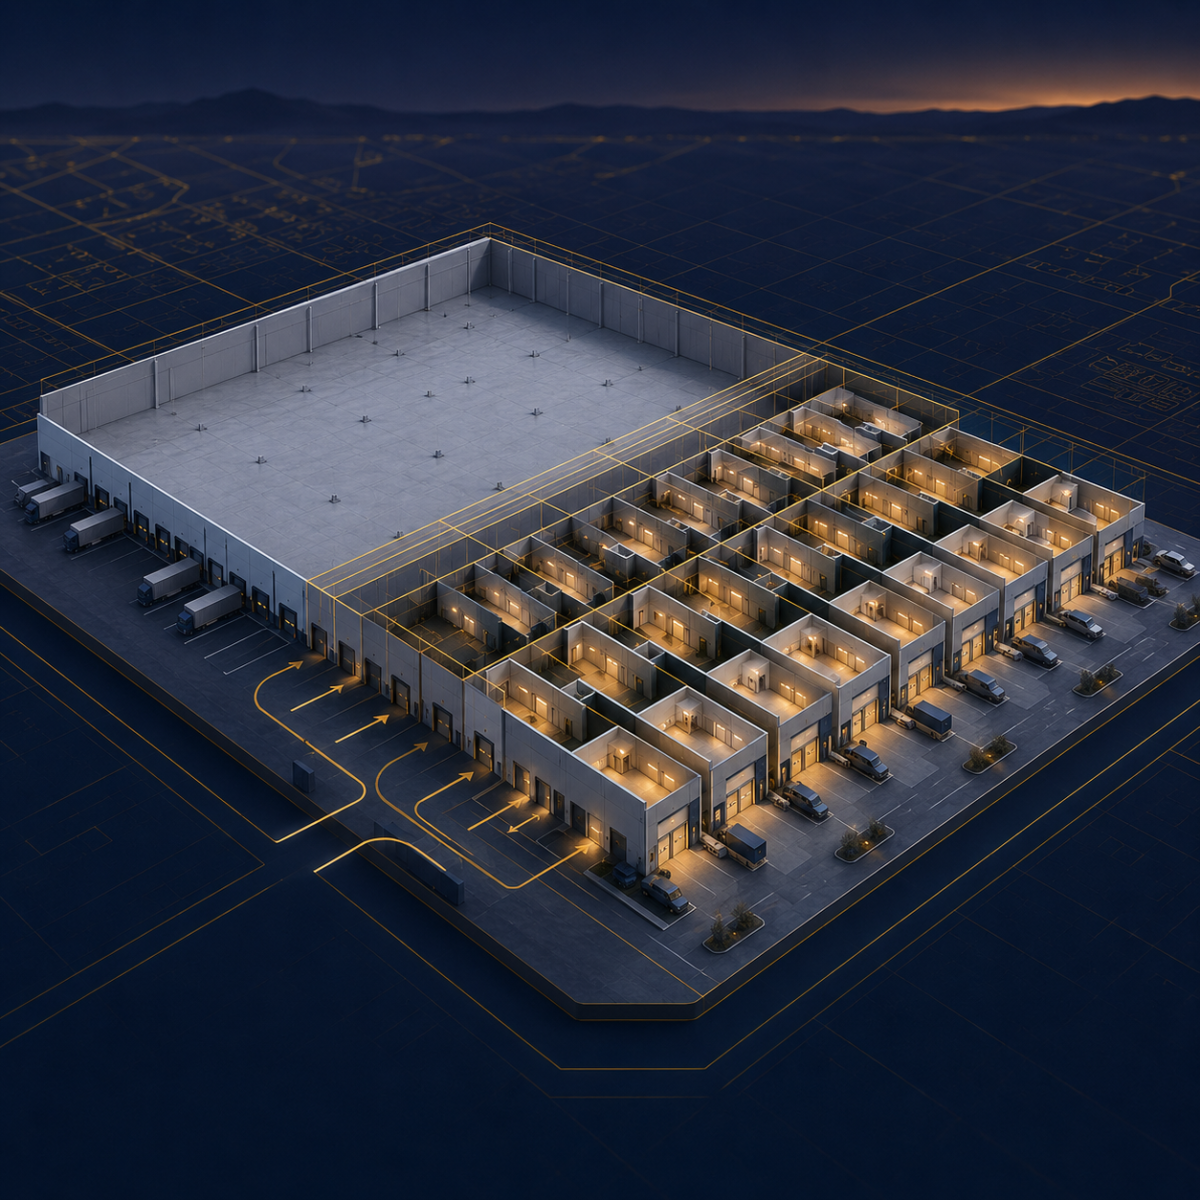
The approximately 105,000-square-foot property is currently a vacant, single-tenant industrial building. Hanson’s plan is to convert it into 10 smaller bays serving the part of the market where tenant demand is deeper, supply is more constrained, and income can be diversified across multiple businesses.

The strategy is straightforward:

Buy into oversupply. Convert into undersupply.

Execution, however, requires more than a compelling phrase. It requires the right basis, the right location, a clearly scoped conversion plan, and enough control to complete the work without allowing debt or market timing to dictate the outcome.

Small-Bay Demand Is Different

Small-bay industrial space supports the businesses that keep metropolitan economies operating.

Typical tenants include contractors, trades, service companies, local suppliers, last-mile operators, and light industrial users. These businesses generally need functional space close to customers, crews, routes, and vendors.

That makes their demand highly location-dependent.

The Chandler investment materials identify a meaningful vacancy difference between the two industrial segments: approximately 6.6% for small-bay space compared with approximately 16% for large-format industrial. They also note that roughly 90% of new industrial construction is concentrated in buildings of 100,000 square feet or more.

The result is a structural imbalance.

Developers continue adding large facilities, while smaller, flexible industrial suites remain difficult to reproduce in established infill corridors. Hanson Capital is not simply underwriting a recovery in overall industrial occupancy. It is repositioning an existing building toward the segment where supply and demand are more favorable.

Why the Chandler Location Matters

The property sits on approximately 5.26 acres within an established Southeast Valley industrial corridor, with direct access to Interstate 10 and Loop 202.

That accessibility matters to local industrial tenants whose operations depend on efficient movement throughout the Phoenix metropolitan area.

The surrounding corridor also benefits from decades of industrial zoning, infrastructure, and established business activity. Major regional investment, including the continued expansion of Intel’s Ocotillo campus, supports a broader ecosystem of suppliers, contractors, service providers, and advanced manufacturing businesses.

This is not a speculative bet on a remote growth market.

It is an infill industrial asset positioned within a mature operating corridor where the existing building can be adapted to serve a wider range of local users.

The Basis Comes Before the Business Plan

Hanson Capital is acquiring the property for approximately $12.5 million, or about $119 per square foot.

That basis is central to the investment thesis.

Estimated replacement cost for comparable industrial space is substantially higher. By acquiring the existing building well below what it would likely cost to recreate today, Hanson begins the conversion with a measure of basis protection before operational improvements are considered.

The projected tenant-improvement and leasing budget is approximately $3.59 million, bringing total capitalization to approximately $17.3 million.

A conversion strategy should not depend on paying a fully stabilized price for an unstabilized asset. There must be sufficient room in the basis to fund the work, manage lease-up risk, and preserve a margin for execution.

At Chandler, the opportunity is not based on assuming the market will make the property more valuable.

It is based on changing what the property offers the market.

From One Vacancy to Ten Income Streams

The current building represents concentrated exposure:

  • One large space
  • One potential tenant
  • One lease expiration
  • One source of property-level income

The conversion changes that profile.

Hanson plans to divide the property into 10 functional industrial bays, creating space for multiple tenants rather than relying on a single occupant.

This is more than a physical renovation.

It changes the asset’s economic structure.

A multi-tenant configuration can diversify lease rollover, reduce dependence on one business, and allow management to address vacancies incrementally instead of replacing an entire building’s income at once.

Hanson is not merely attempting to fill existing vacancy.

The firm is repositioning the property from a more competitive large-format category into an undersupplied small-bay segment where functionality, access, and unit size can support broader tenant demand.

Why All-Cash Execution Matters

The acquisition and conversion are structured without debt.

That does not eliminate redevelopment or leasing risk. It does, however, remove a significant source of external timing pressure.

Without near-term lender maturities, refinancing requirements, or floating-rate exposure, Hanson retains greater control over the pace of construction, leasing, stabilization, and the eventual exit decision.

That flexibility is especially important in a conversion project.

Operational plans rarely unfold in a perfectly linear sequence. Permitting, contractor schedules, tenant requirements, and lease negotiations can affect timing. An all-cash structure allows management to respond to those realities without a lender forcing decisions that may not serve the long-term investment thesis.

Debt can be a useful tool.

It should not become the business plan.

A Familiar Hanson Capital Playbook

The Chandler strategy reflects a process Hanson Capital has applied before: acquire functional industrial real estate at an irreplaceable basis, solve a product-market mismatch, and create a more diversified income profile through active execution.

The opportunity is not speculative development. The existing building, land, access, and industrial use are already in place.

The work is targeted.

Hanson has evaluated the asset, obtained initial municipal feedback, scoped the construction plan, and approached the conversion through the same operational lens used across its small-bay portfolio.

That does not make execution automatic. It makes the risks more identifiable and manageable.

Why Chandler Advanced

Chandler was evaluated alongside other potential replacement properties during Hanson Capital’s broader 1031 exchange process.

Not every candidate advanced.

Point West was declined after physical diligence revealed capital exposure that could not be resolved at the required basis. San Marcos was declined after pricing and tenant dynamics compressed the yield and reduced the remaining value-add opportunity. Scottsdale advanced after unexpected capital items were quantified and addressed with the seller.

Chandler emerged as a high-conviction opportunity because the basis, location, conversion strategy, and capital structure remained aligned after scrutiny.

The 1031 timeline did not make Chandler investable.

The underwriting did.

Strategic Takeaway

The strongest real estate opportunities are not always found by buying the segment with the most attention.

Sometimes they are created by recognizing where an existing asset no longer matches the demand around it.

At 235 S. 56th Street, Hanson Capital is acquiring large-format industrial exposure below replacement cost and repositioning it into smaller, more flexible bays supported by infill tenant demand.

The plan combines disciplined basis selection, tenant diversification, operational control, and all-cash execution.

That is not a passive bet on industrial appreciation.

It is a targeted strategy to move an asset from oversupply into undersupply through execution.

Discuss Current Industrial Opportunities

Schedule a discussion with Hanson Capital to evaluate current small-bay industrial opportunities and potential 1031 exchange replacement property options.

Categories
Real Estate

Fed Pause Leaves CRE Borrowing Costs at Elevated Levels

The Federal Reserve has held its benchmark rate steady at approximately 3.5%, but commercial real estate borrowers are not feeling much relief. The 10-year Treasury yield climbed to near 4.63% in early August, and because most commercial mortgages are priced off long-term Treasury yields rather than the Fed funds rate, borrowing costs remain elevated. The result is a continued tightening of financing conditions for property owners and buyers alike, constraining both transaction volume and refinancing activity across the commercial real estate market.

Our Take

For private market investors, the current environment illustrates an important and often misunderstood disconnect: the Federal Reserve’s benchmark rate and the actual cost of borrowing for commercial real estate are not the same thing. With the 10-year Treasury near 4.63% in early August, financing conditions remain meaningfully tight even as the Fed holds steady. That gap matters, and understanding it is central to reading where opportunity lies right now.

From an underwriting perspective, elevated long-term yields affect nearly every decision in commercial real estate. Acquisition pencils get harder to sharpen when debt service consumes a larger share of property income. Owners holding floating-rate debt or facing near-term loan maturities feel the pressure most acutely, which is exactly the kind of dislocation that creates opportunity for patient capital with the discipline to move carefully.

For investors, this environment is doing something useful, even if it does not feel that way on the surface. Higher borrowing costs are filtering out overleveraged buyers and speculative deals that would not hold up under scrutiny. What remains are assets with genuine cash flow and sponsors with the wherewithal to close. That narrows the field and improves the quality of what reaches a disciplined underwriter’s desk.

In practical terms, the spread between the Fed funds rate and long-term Treasury yields serves as a reminder that monetary policy does not directly control the financing environment in commercial real estate. The market does. And right now, the market is telling buyers, lenders, and owners to proceed with care. The key takeaway is that durable assets acquired with conservative leverage and strong in-place income are built precisely for moments like this one.

Source: Fed Pause Leaves CRE Borrowing Costs at Elevated Levels — Yahoo Finance

If you’re curious about how our approach could fit into your portfolio, schedule a call to connect with our team. We’d love to talk through what we’re seeing and where we’re going next.